IRS Visibility into Digital Payments: What Small Businesses and Freelancers Must Know
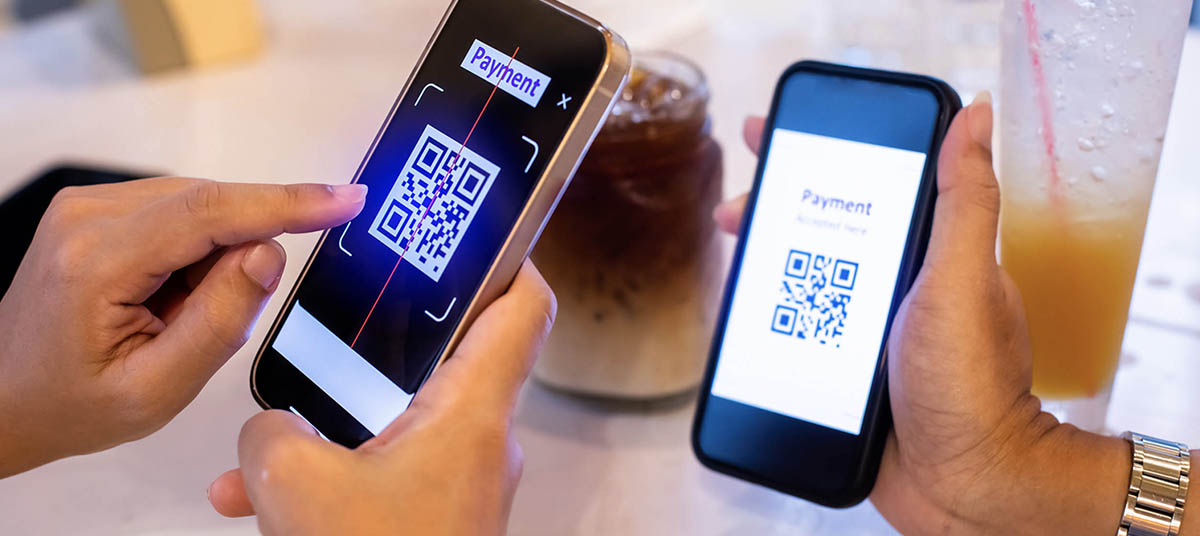
It usually begins with a casual assumption that digital transactions are somehow separate from the traditional tax world. We often hear small business owners in Cranford and across New Jersey say they only made a small amount of side income, or that because clients paid via Venmo, the money remains “off the books.” There is a common misconception that if a formal tax form doesn’t arrive in the mail, the income doesn’t exist in the eyes of the IRS.
The reality is that payment apps are not invisible. While they offer speed and convenience, they also create a digital paper trail that the IRS is increasingly focused on. For freelancers, creators, and gig workers, the casual nature of these platforms often masks the rigorous reporting requirements of the Internal Revenue Code. Whether you are a consultant or an online seller, understanding how these transactions are reported is the first step toward avoiding a stressful audit or a surprise tax bill.
The Illusion of Invisibility in the Digital Economy
Over the last decade, digital payment platforms have evolved from personal tools into the financial backbone of the modern economy. Independent contractors accept Venmo for quick settlements, creators rely on Stripe for subscriptions, and online sellers use Shopify or Square to manage global transactions. Because these apps don’t feel like traditional banking, it’s easy to treat the income as “extra” money rather than business revenue.
However, the tax law is clear: under IRC Section 61, all income is taxable from whatever source derived, unless specifically excluded by law. This means that even if you never receive a 1099-K, you are legally obligated to report that income on your tax return. The shift away from traditional W-2 payroll means there is no HR department to withhold taxes for you. Every dollar that hits your Cash App or PayPal account from a customer is potentially subject to both income tax and the 15.3% self-employment tax.
Decoding the 1099-K Reporting Thresholds
There has been significant confusion surrounding Form 1099-K reporting limits. While recent legislative proposals aimed to drop the reporting threshold to a mere $600, the IRS has repeatedly delayed the implementation of these lower limits to allow for a smoother transition. For the current tax year, the federal reporting threshold for third-party settlement organizations (TPSOs) generally remains at $20,000 in gross payments and more than 200 transactions.
However, many business owners are caught off guard by state-specific rules. Several states have implemented much lower thresholds, meaning you might receive a 1099-K even if you didn’t hit the federal $20,000 mark. Furthermore, traditional merchant processors—the ones used for credit card swipes in a physical store—operate under different rules and may report transactions regardless of the dollar amount. At TaxDrx, we frequently see clients surprised by these forms because they assumed the “delay” meant they were exempt from reporting altogether.
The Critical Distinction Between Personal and Business Transfers
One of the biggest risks for small business owners is “commingling”—the mixing of personal and business funds. When you use the same Venmo account to accept payment for a consulting gig and to get reimbursed by a friend for dinner, you are creating a bookkeeping nightmare. If the IRS were to examine your records, the burden of proof is on you to demonstrate which deposits are taxable income and which are non-taxable gifts or reimbursements.
Zelle presents a unique case in this landscape. Unlike PayPal or Venmo, Zelle typically does not issue Form 1099-K because it acts as a bank-to-bank transfer service rather than a third-party settlement network. But do not mistake a lack of reporting for a lack of taxability. If you receive $5,000 via Zelle for professional services, that $5,000 is still reportable business income. The platform used to move the money does not change the nature of the transaction in the eyes of the law.

Why Gig Workers and Creators are Especially Vulnerable
Gen Z entrepreneurs, influencers, and rideshare drivers are often the most impacted by these digital paper trails. Because these income streams are fragmented across multiple apps, it is incredibly easy to lose track of the total gross revenue. Without a proactive system for estimated tax planning, these individuals often face a “double hit” at tax time: the standard income tax plus the full weight of self-employment taxes that weren’t withheld throughout the year.
We’ve seen many creative professionals overlook significant deductions—like home office expenses, equipment depreciation, or platform fees—simply because their records were scattered across five different payment apps. This results in either overpaying the IRS or underreporting income and triggering penalties and interest. Organization isn’t just about compliance; it’s about protecting your cash flow and ensuring you aren’t leaving money on the table.
Building a Resilient Financial System for Your Business
The solution to digital payment anxiety isn’t to avoid the apps; it’s to wrap them in a professional system. Smart business owners in the Cranford area are moving away from “spreadsheet guessing” and toward automated bookkeeping. By segregating business activity into a dedicated bank account and connecting that account to a professional ledger, you create a clear audit trail that protects you and provides clarity on your true profitability.
Proactive tax planning is the ultimate defense. By reviewing your income mid-year, you can adjust your estimated payments and identify tax-saving opportunities before the December 31st deadline. Our team at TaxDrx specializes in helping solopreuners and small businesses untangle these digital webs, ensuring that your Venmo and PayPal activity is correctly categorized and optimized for maximum savings.
Secure Your Peace of Mind Through Proactive Planning
The digital economy has made it easier than ever to start a business, but it has also made tax compliance more complex. If your income flows through multiple digital platforms, now is the time to review your strategy before year-end pressure mounts. Identifying gaps in your bookkeeping early can prevent costly IRS notices and provide the financial clarity you need to grow.
If you are ready to move beyond the stress of scattered transactions and want to uncover real tax savings, our team is here to help. Schedule a consultation with TaxDrx today to learn how our monthly bookkeeping and strategic tax advisory services can simplify your financial life and protect your hard-earned income.
Want tax & accounting tips and insights?
Sign up for our newsletter.
TAX DRx at a Glance
Our expertise is widespread and we have multiple office locations to make it convenient for you to get help. You can find us at:
TAX DRx Corporate Headquarters
Cranford, NJ 07016
(Grd St Pkwy - Ext 136)
NYC - MSG Office
New York, NY 10001
(8th Ave & 34th St.)
(Sbwy A, B, C, LIRR, etc.)
TAX DRx - Hillside
Hillside, NJ 07205
(Corner of Conklin Ave)
TAX DRx, dba/ TaxJohn
121 Park Ave
Plainfield, NJ 07060